BDC Woveo $10M Microlending: Loans up to $25,000 for Canadian SMBs (Oct 2026)
BDC and Woveo launched a $10M microlending facility on 8 October 2026: loans up to $25,000 Canada-wide excluding Quebec. Eligibility signals, who it helps, and what operators should do next.
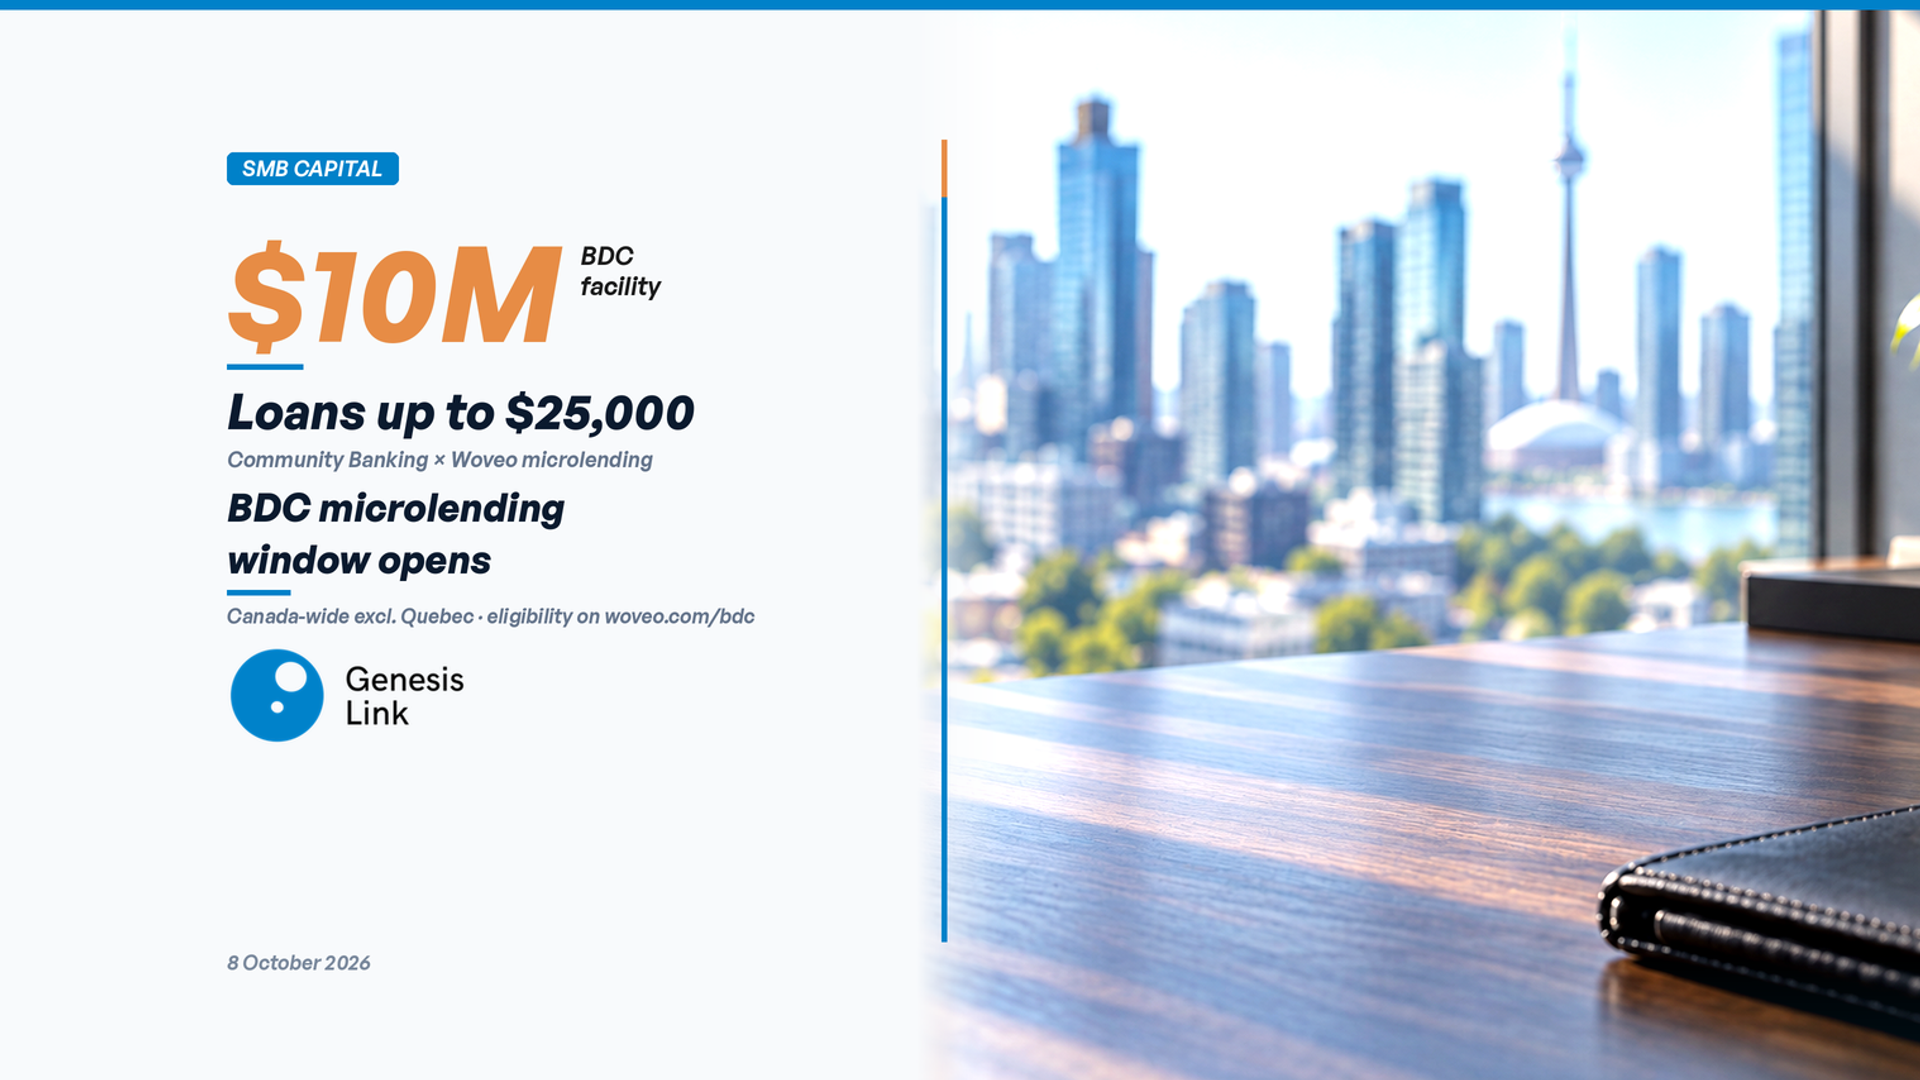
On 8 October 2026, Woveo announced a $10 million microlending initiative with the Business Development Bank of Canada (BDC). Loans of up to $25,000 are available to eligible entrepreneurs across Canada, excluding Quebec. The programme sits under BDC’s Community Banking network, where Woveo is listed as a nationwide partner (excluding Quebec).
This is GenesisLink’s first Pillar B news brief: Canadian small-business capital, not an immigration draw. It matters for immigrant operators who are already running a Canadian company, and for domestic SMBs that need a first or second microloan while they build credit and operating history.
What changed
- Facility size: $10 million lending initiative (Woveo / BDC announcement, 8 October 2026).
- Loan size: up to $25,000 per borrower (programme materials).
- Geography: Canada-wide, excluding Quebec (BDC Community Banking partner list and Woveo programme page).
- Channel: Application and eligibility check at woveo.com/bdc; BDC Community Banking overview at bdc.ca Community Banking.
BDC’s Community Banking page frames the mandate as financing and advice through trusted partners for businesses that “don’t always fit the mold of standard business models.” Woveo appears on that partner list with a direct programme link. The 8 October release positions the facility as a way to establish credit histories and move toward larger mainstream financing over time.
Published eligibility signals (high level)
The Woveo programme page lists screening criteria. These are not a credit decision and are not tax, legal, or accounting advice. Confirm live on the application flow before you act:
The release also notes AI-assisted underwriting that can use cash-flow information, credit bureau data, business-performance signals, and social collateral. Treat that as product description from the issuer, not a guarantee of approval speed or outcome.
Who this helps
- Immigrant-owned SMBs (newcomer operators): Useful after the company is live in Canada with roughly a year of operations, revenue, and a credit trail. A $25,000 microloan will not replace equity for a PNP performance agreement or a multi-location expansion plan, but it can fund inventory, equipment deposits, marketing tests, or working-capital gaps while the file builds toward larger BDC or bank products.
- Domestic SMBs: Same instrument. Operators who are underserved by conventional underwriting for small ticket sizes are the explicit design audience in BDC’s Community Banking language.
- Both: Pair capital readiness with clean books, a defensible use-of-funds memo, and realistic job/revenue tracking. That package is what lenders and later immigration performance reviews both read.
What our files show
Operators who treat “funding” as a last-minute form usually fail eligibility screens on documentation, not ambition. The files that move faster keep monthly revenue proof, a short use-of-funds note tied to real costs, and a clear owner story that matches the CRA and corporate record. GenesisLink packages that business layer for immigrant and domestic SMBs; we do not underwrite loans or decide grants.
Context practitioners should hold
The announcement cites OECD Financing SMEs and Entrepreneurs 2026 figures showing the share of new Canadian business lending directed to SMEs fell from 16% in 2011 to 5.8% in 2024. That is the public case for micro facilities. It does not mean every applicant is approved, and it does not replace bank, credit-union, or other BDC Community Banking partners (RBC, TD, Alterna, Futurpreneur, FACE, and others listed on BDC’s page).
Separately, Agriculture and Agri-Food Canada’s Food Hub Program under the Food-Link Fund shows an intake window from 14 October 2026 to 11 December 2026 (11:59 pm Pacific), with cost-share rules and possible higher AAFC share for majority underrepresented ownership. That is a different instrument (infrastructure / food hub, up to $25 million per organization over the programme life) and is only relevant if the business model is food-hub infrastructure. Primary page: agriculture.canada.ca Food Hub Program. Do not conflate it with the BDC–Woveo microloan.
What to do next
- Read BDC Community Banking and confirm Woveo is the right partner for your province (Quebec excluded on this product).
- Check live eligibility at woveo.com/bdc. Do not rely on a secondary blog summary alone.
- Assemble revenue, banking, and ownership documents before you apply. If monthly revenue or credit is below the published signals, fix the business facts first.
- Speak to your accountant and, where needed, counsel on debt capacity and tax treatment. GenesisLink does not provide tax, legal, or lending advice.
- If you are on a C11, ICT, or PNP business path, align any new debt with your stated business plan and job-creation logic so the operating story stays consistent.
GenesisLink’s role
GenesisLink is a Canadian business consulting firm. We support immigrant entrepreneurs and domestic SMBs on viability, documentation, marketing and operations, and funding-readiness packaging alongside RCICs, lawyers, accountants, and lenders. We are not BDC, not a lender, not CRA, and not a grant decision-maker. Across 300+ business files and 20+ RCIC partnerships, the pattern is the same: capital conversations go better when the commercial file is already coherent.
Start a business assessment · Book a working session
Sources (primary): Woveo press release, 8 October 2026; CNW distribution; Woveo × BDC programme page; BDC Community Banking (Woveo listed under financial institution partners); AAFC Food Hub Program (related intake note only).
Discussion
Be the first to comment.
Add a comment