BDC and Woveo Launch $10M Microlending Program for Canadian Small Businesses
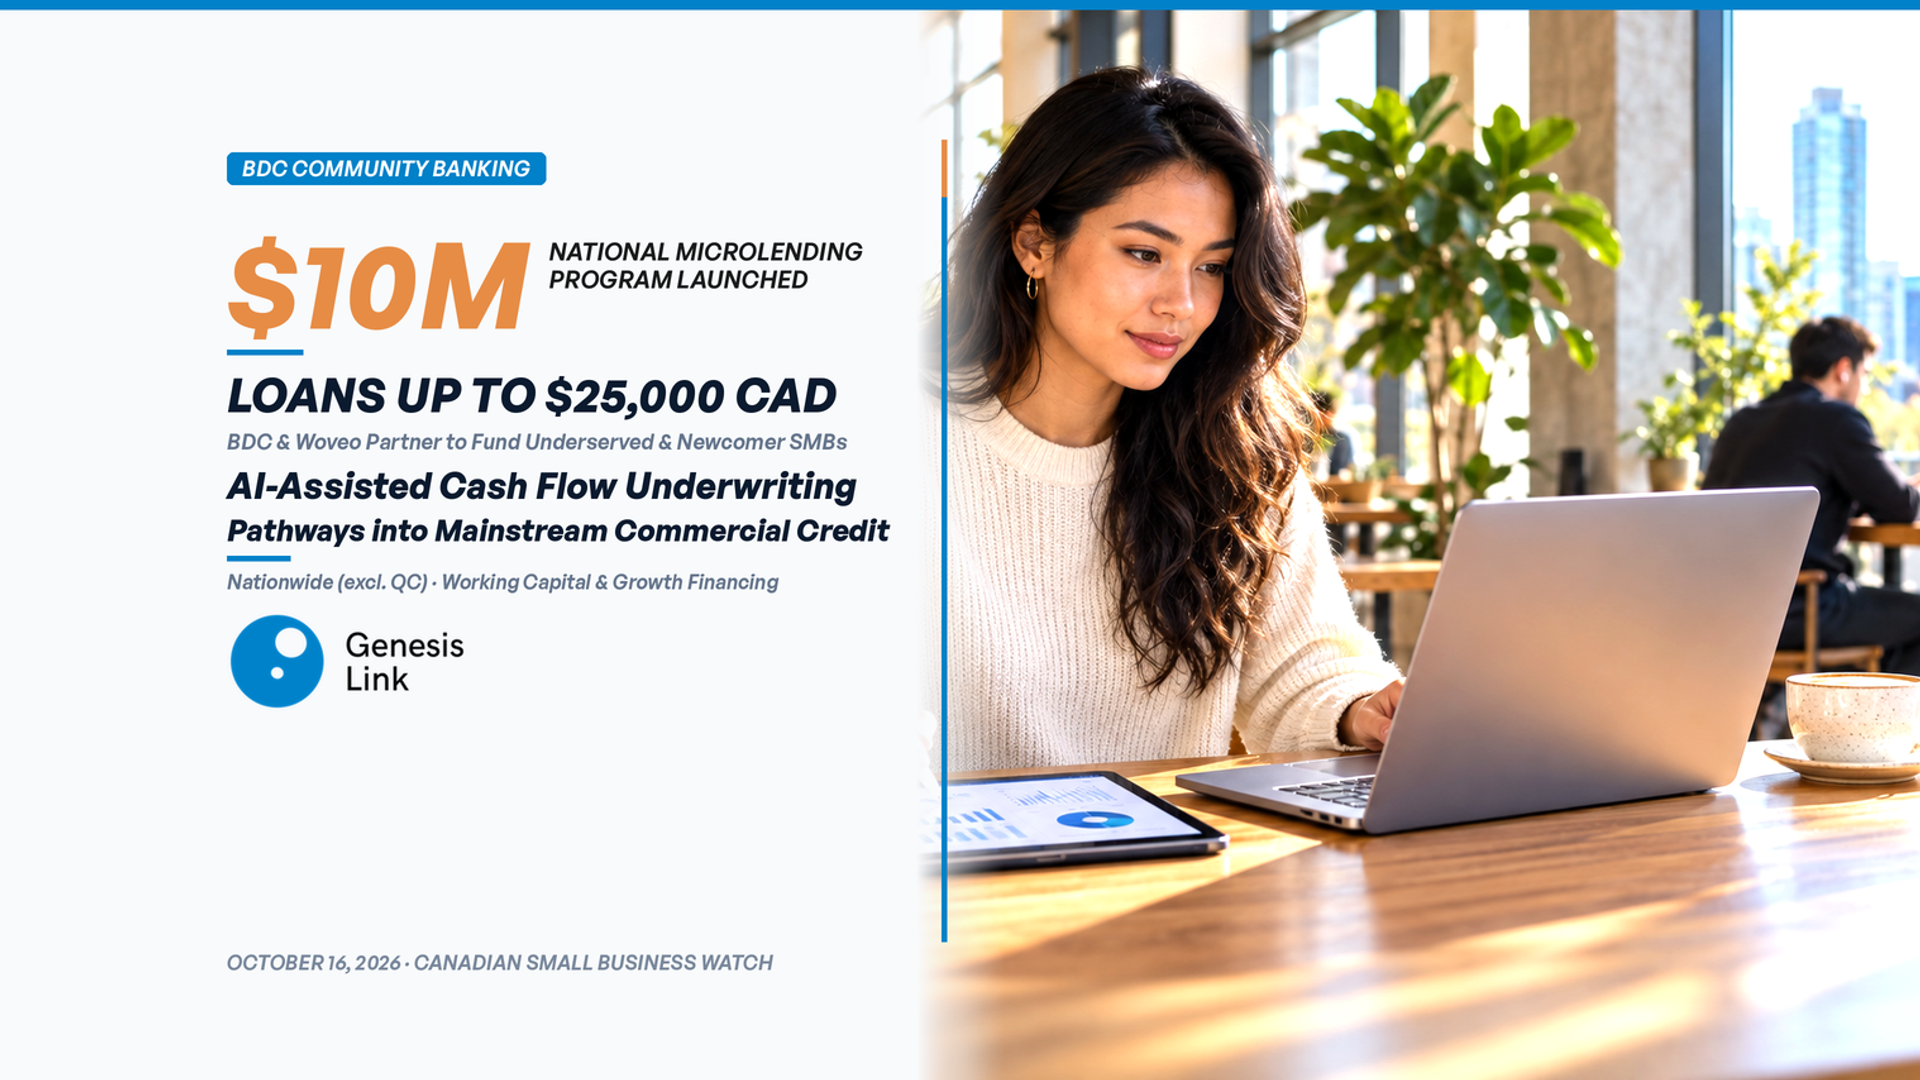
BDC and Woveo introduce a $10M national microlending program providing loans up to $25,000 for newcomer and underserved Canadian entrepreneurs using AI-assisted cash-flow underwriting.
60-Second Key Takeaways for Canadian Operators and Advisors
- Program Size & Cap: $10 million national microlending deployment between Business Development Bank of Canada (BDC) and fintech platform Woveo, offering loans up to $25,000 CAD per business.
- Target Recipients: Underserved entrepreneurs, newcomer business founders, younger operators, and small firms lacking extensive Canadian commercial credit history.
- Alternative Underwriting: Employs AI-assisted cash-flow analysis, real-time operating metrics, and community accountability rather than strict traditional collateral or 3-year historical balance sheets.
- Geographic Scope: Nationwide availability across all Canadian provinces and territories, excluding Quebec.
- Strategic Growth Trajectory: Program reports a 98% historic repayment rate across 1,200+ facilitated loans, designed explicitly to graduate growing firms into conventional tier-1 commercial banking credit.
The Business Development Bank of Canada (BDC) and Calgary-based financial technology company Woveo have launched a $10 million national microlending initiative designed to close the credit gap for underserved and newcomer business owners across Canada. Under the program, eligible small businesses can access working capital loans of up to $25,000 CAD through an accelerated underwriting framework that evaluates real-time cash flow, operational performance, and community accountability rather than relying solely on rigid credit bureau scores or immovable asset collateral.
For immigrant entrepreneurs operating under federal or provincial business pathways, as well as domestic small-to-medium enterprises (SMBs), accessing early debt capital remains one of the steepest hurdles in the Canadian market. This initiative operates under BDC's Community Banking umbrella, creating a structured bridge between early-stage microfinance and long-term institutional commercial banking.
What Is the Structural Problem in Canadian Small Business Lending?
Smaller operating businesses have faced increasingly restricted credit access over the past decade. Data from the OECD's Financing SMEs and Entrepreneurs 2026 report indicates that the proportion of new Canadian business lending allocated to small and medium-sized enterprises contracted from 16% in 2011 to just 5.8% in 2024. For micro-businesses and early-stage operating companies seeking loans under $50,000, traditional underwriting costs often exceed the economic return for major commercial lenders.
This market friction disproportionately impacts newcomer entrepreneurs, international founders who recently transitioned to Canada, and younger business owners. While these operators frequently demonstrate viable commercial models, consistent daily sales, and active customer demand, their lack of a multi-year Canadian personal and commercial credit history often triggers automated rejections from conventional institutions.
Research Benchmark:
According to OECD and SME finance evaluations, small businesses receiving combined access to structured capital and ecosystem advisory demonstrate survival rates of approximately 65%, compared to 46% for unassisted peers. Furthermore, firms securing timely working capital more than double their annual revenue growth and nearly triple their job creation rates over a three-year period.
How Does the BDC-Woveo $10M Microlending Program Work?
The initiative couples capital from Canada's development bank with Woveo's proprietary digital underwriting architecture. Instead of conditioning loan approval exclusively on rigid credit scores or fixed physical assets, the underwriting model evaluates multiple real-time operational indicators:
- Real-Time Cash-Flow Intelligence: Direct analysis of operating bank inflows, recurring revenue consistency, and merchant transaction health.
- Operational Performance Signals: Vendor settlement patterns, supplier relationship duration, and day-to-day balance stability.
- Social Collateral & Ecosystem Validation: Integration with trusted local community business groups and ecosystem partners who assist in vetting and mentoring borrower enterprises.
- Automated Digital Verification: Minimizing administrative overhead to deliver lending decisions within days rather than the weeks required by traditional commercial banking channels.
Who Qualifies and Who Does This Serve?
The program serves commercial entities operating across two key groups:
- Newcomer and Immigrant Business Operators: Founders who have established operations in Canada (including work permit holders operating businesses under C11, provincial business streams, or recent permanent residents) who have strong operational momentum but lack 3 to 5 years of domestic credit history.
- Domestic Small Business Owners: Early-stage Canadian entrepreneurs in services, retail, technology, trades, and food sectors who require working capital between $5,000 and $25,000 CAD to purchase inventory, upgrade equipment, or manage cash-flow cycles without taking on high-interest merchant cash advances.
Applicants must operate an active Canadian business registered outside the province of Quebec and demonstrate recurring operating revenue through verifiable commercial accounts.
What Our Files Show: The Working Capital Barrier for Newcomer Operators
Across more than 300 client files managed at GenesisLink, working capital accessibility in months 6 through 18 of Canadian operations is a primary determinant of business viability. Immigrant operators frequently capitalize their initial launch via foreign equity transfers, but face an unexpected freeze when seeking short-term local credit lines to finance seasonal inventory or initial payroll expansion. Establishing an on-time borrowing track record with institutional backing like BDC creates the verifiable commercial credit file required for subsequent tier-1 bank debt and commercial lease expansions.
How Does This Fit Alongside Federal Programs and Tax Relief?
This microlending initiative complements recent federal measures introduced for Canadian business operators in late 2026. Yesterday's announcement of the Productivity Mega Deduction, providing 100% immediate first-year tax write-offs for capital equipment, clean energy machinery, and digital software, allows Canadian businesses to deduct investments in full. For small businesses that lacked cash on hand to purchase technology or production machinery, microloans up to $25,000 provide the exact liquidity required to acquire eligible capital assets and immediately capture the 100% tax write-off.
Additionally, for foreign entrepreneurs operating under C11 or PNP agreements, demonstrating independent third-party debt financing from an entity partnered with a Crown corporation (BDC) reinforces evidence of commercial establishment and active business execution during work permit extension and permanent residence nomination reviews.
Action Checklist: How Operators Should Prepare Their Financing Package
Small business owners and newcomer operators planning to apply should prepare the following operational documentation:
- Commercial Bank Account Data: Connect or provide at least 6 to 12 months of consecutive operating transaction statements showing regular cash inflows and customer settlement.
- Business Registration & Tax Number: Active federal business number (BN) and provincial enterprise registration confirming operational standing outside Quebec.
- Use of Funds Rationale: A clear, concise commercial statement detailing how the $5,000 to $25,000 facility will be deployed (e.g., initial inventory order, essential tooling, website and POS software rollout, or marketing campaign).
- Entity Leadership Overview: Valid identification and business operational details for majority beneficial owners.
Operators can evaluate their eligibility and submit digital applications directly through the official portal at woveo.com/bdc and review BDC Community Banking resources at bdc.ca/en/about/what-we-do/community-banking.
Frequently Asked Questions (FAQ)
Can immigrant business owners on a work permit apply for this loan?
Yes, provided the business is legally registered and operating in Canada (outside Quebec), maintains active Canadian commercial banking transactions, and the applicant holds valid legal operational status in Canada.
Does this microloan require personal real estate collateral?
No. Unlike standard commercial term lending or large business loans, the program utilizes cash-flow metrics, operational track record, and social collateral, eliminating the requirement for residential or commercial property charges.
Why is Quebec excluded from this specific deployment?
The program is currently structured across common-law provincial jurisdictions under BDC's community partner agreement. Businesses based in Quebec can access dedicated provincial equivalents through BDC partners such as Evol and Desjardins.
How does this impact an operator's Canadian credit score?
On-time repayment data is reported through established credit reporting frameworks, allowing newer businesses to build a verifiable corporate credit profile that paves the way for larger traditional bank facilities as revenue scales.
What is the expected approval timeline?
Because underwriting leverages AI-assisted analysis of real-time account data and automated verification, initial qualification decisions are processed substantially faster than traditional multi-week commercial bank reviews.
Structuring Your Canadian Enterprise for Growth and Compliance
GenesisLink works alongside immigration counsel, accountants, and commercial lenders to package compliant, investment-ready business models for newcomer entrepreneurs and growing Canadian firms.
Recent News

 October 15, 2026


More on Small business growth
 NewsCanada Introduces Productivity Mega Deduction: 100% Immediate Expensing for Business Investments
 NewsFedDev Ontario Launches Regional AI Initiative Intake: Up to $5M in SME Funding for Artificial Intelligence Adoption and Scaling
 NewsWomen Entrepreneurship Loan Fund Renewed: $30M in Federal Microloans for Canadian SMEs
 NewsBDC Woveo $10M Microlending: Loans up to $25,000 for Canadian SMBs (Oct 2026)
 BlogWhy Most PNP Intent-to-Reside Sections Are Written Backwards
Discussion
Be the first to comment.
Add a comment