Canada Introduces Productivity Mega Deduction: 100% Immediate Expensing for Business Investments
IRCC Minister Metlege Diab and Finance Minister Champagne announce the permanent Productivity Mega Deduction, expanding immediate 100% expensing to over 65% of business assets and cutting the investment tax rate to 6.4%.
60-Second Practitioner Takeaways
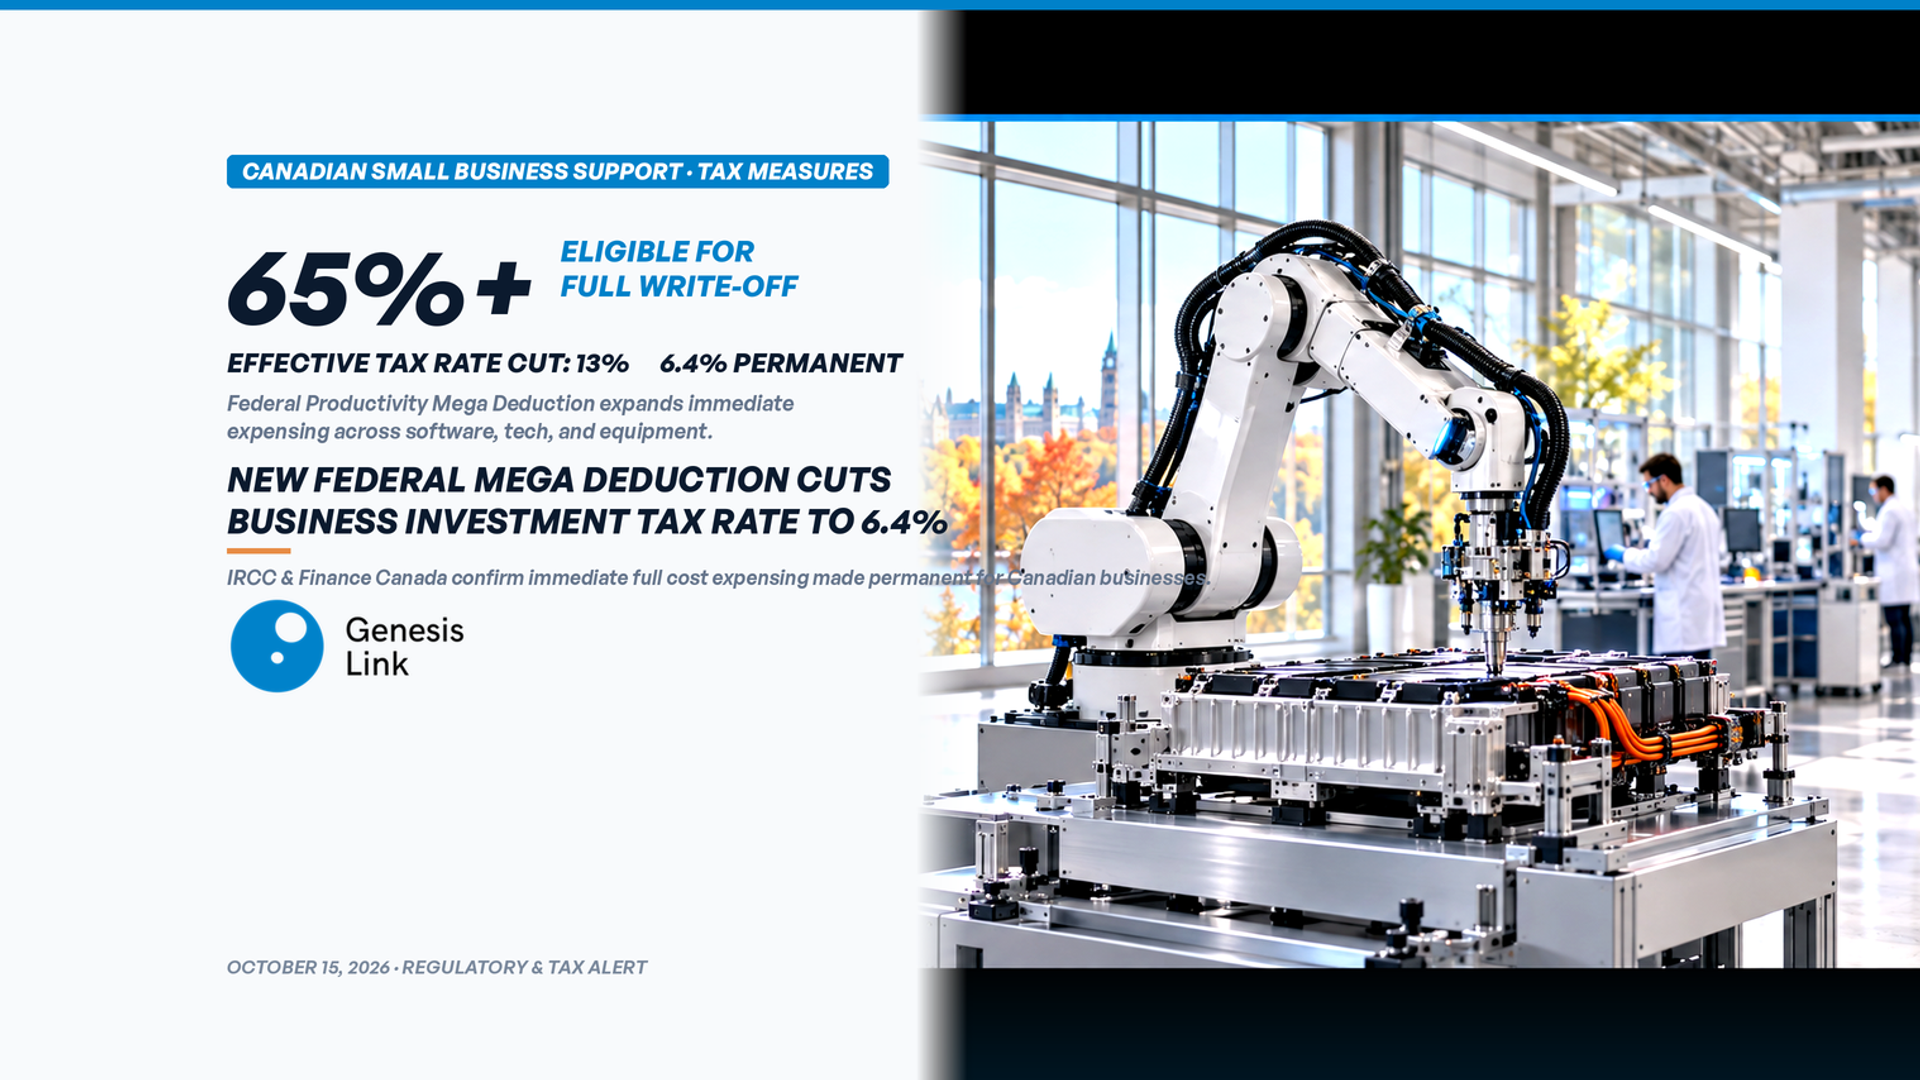
- Permanent Immediate Expensing: The Government of Canada has made immediate full-cost expensing permanent for depreciable business investments, moving from temporary accelerated write-offs to a permanent statutory foundation.
- Asset Coverage Expanded to 65%+: Assets eligible for 100% year-one Capital Cost Allowance (CCA) deduction expand from roughly 15% to over 65%, including software, computer hardware, patents, R&D facilities, clean-tech, vehicles, and industrial machinery.
- Marginal Tax Rate Dropped to 6.4%: Canada's marginal effective tax rate (METR) on new business investment drops from 13% to 6.4%, the lowest in the G7 and less than half of the United States rate.
- Impact for C11, ICT, and Immigrant Operators: New enterprises established by immigrant entrepreneurs under C11, ICT, or PNP streams can immediately write off 100% of upfront capital equipment, IT infrastructure, and intellectual property acquisitions, significantly lowering Year 1 tax liabilities and preserving operational cash flow.
In a major federal announcement with profound implications for both domestic Canadian small businesses and newly established foreign entrepreneur enterprises, Immigration Minister Lena Metlege Diab and Finance Minister François-Philippe Champagne have detailed the implementation of Canada’s new Productivity Mega Deduction.
Described as one of the most substantial structural shifts to Canada’s corporate tax landscape in half a century, the measure permanently cuts the cost of acquiring capital assets, technology, and productivity infrastructure across all Canadian provinces and territories.
What Is the Productivity Mega Deduction?
Under Canada's standard Capital Cost Allowance (CCA) system administered by the Canada Revenue Agency (CRA), businesses are required to depreciate capital investments gradually over multiple tax years depending on the asset's prescribed CCA class. This multi-year write-off schedule often defers tax deductions and constrains liquidity during a business's critical growth phases.
The new Productivity Mega Deduction fundamentally restructures this framework by allowing businesses of all sizes to immediately deduct 100% of the cost of eligible investments in the first year the asset becomes available for operational use.
Why Did the Immigration Minister Announce a Major Corporate Tax Reform?
The joint announcement by Immigration, Refugees and Citizenship Canada (IRCC) Minister Lena Metlege Diab alongside Finance Minister François-Philippe Champagne highlights an increasingly deliberate strategic convergence between federal immigration policy and Canadian economic productivity.
With Canada recalibrating its temporary resident targets and emphasizing high-value economic establishment, the federal government is aligning fiscal policy directly with business immigration readiness. For international founders entering through C11 Significant Benefit work permits, Intra-Company Transfers (ICT), or Provincial Nominee Program (PNP) business streams, Canada must offer an undeniably competitive environment to deploy capital and hire local talent.
What Our Files Show
Across more than 300 active business immigration files and consulting engagements managed by GenesisLink, capital deployment timing is frequently the primary operational vulnerability in Year 1. When foreign investors establish Canadian subsidiaries, standard tax depreciation models restrict immediate deduction benefits, tying up liquidity precisely when the enterprise needs working capital to meet payroll commitments. Under the new Productivity Mega Deduction, initial capital purchases, including proprietary software licenses, servers, diagnostic tools, and operational vehicles, can be expensed at 100% in Year 1 financial statements. This immediate deduction shields initial operating revenue from early corporate income taxation, significantly strengthening the business viability defensibility required at work permit extension stages.
Eligible Capital Assets: What Can Canadian Businesses Expense Immediately?
The expansion from 15% to more than 65% of asset classes covers practically all key technology and infrastructure investments essential for modern commercial operations:
- Computer Hardware & Telecommunications: Servers, desktop workstations, networking gear, and fibre-optic systems (CCA Classes 50, 46, and related IT categories).
- Enterprise Software & Systems: Custom business software, enterprise ERP platforms, and digital management systems (CCA Class 12 / Class 52).
- Intellectual Property & Patents: Acquired patents, commercial processes, and technology licensing rights (CCA Class 44).
- Research & Development Infrastructure: Clean-tech testing equipment, specialized laboratory machinery, and industrial prototypes.
- Industrial Machinery & Advanced Manufacturing: Automation equipment, robotic assembly systems, and advanced processing tools.
- Commercial Vehicles & Transportation: Zero-emission commercial vehicles, heavy transport equipment, and essential logistics assets.
Implications for RCICs, Immigration Lawyers, and Business Advisors
For immigration practitioners advising foreign entrepreneurs and commercial corporate clients, this tax overhaul directly shapes how business plans and investment schedules should be drafted:
- Optimize Capital Deployment in Year 1 Financials: Rather than spreading equipment and technology acquisitions across multi-year projections, business plans should structure upfront capital investment to maximize year-one write-offs. This directly enhances Year 1 cash flow stability.
- Strengthen the "Significant Benefit" Case for C11 Files: Demonstrating that an immigrant entrepreneur is investing in productivity-enhancing capital assets (qualifying under federal priority expensing) provides clear evidentiary proof that the enterprise aligns with federal economic modernization priorities under IRPR 205(a).
- Leverage Canadian Marginal Effective Tax Advantages: With Canada’s marginal effective tax rate on new business investment reduced to 6.4%, compared to more than 13% in the United States, multinational clients evaluating North American expansion under ICT pathways have an explicit, quantified tax incentive to locate key infrastructure in Canada.
Action Checklist for Business Immigration and SME Clients
- Audit Planned 2026-2027 Capital Expenditures: Review all planned equipment, hardware, and IP acquisitions to confirm qualifying CCA classes under the expanded 65% threshold.
- Align Investment Timelines with Available-for-Use Rules: Ensure equipment and technology purchases are delivered and operational within the tax year to trigger the immediate 100% deduction.
- Consult Corporate Tax and Business Planning Partners: Coordinate with qualified Canadian tax accountants and business consulting advisors to structure asset purchases effectively against expected operating revenues.
Structuring an Immigration-Grade Business Case in Canada?
GenesisLink partners with RCICs, immigration lawyers, and international entrepreneurs to build compliant, commercially sound business models and defensible documentation. Discover how our business execution frameworks support your client files.
Discussion
Be the first to comment.
Add a comment